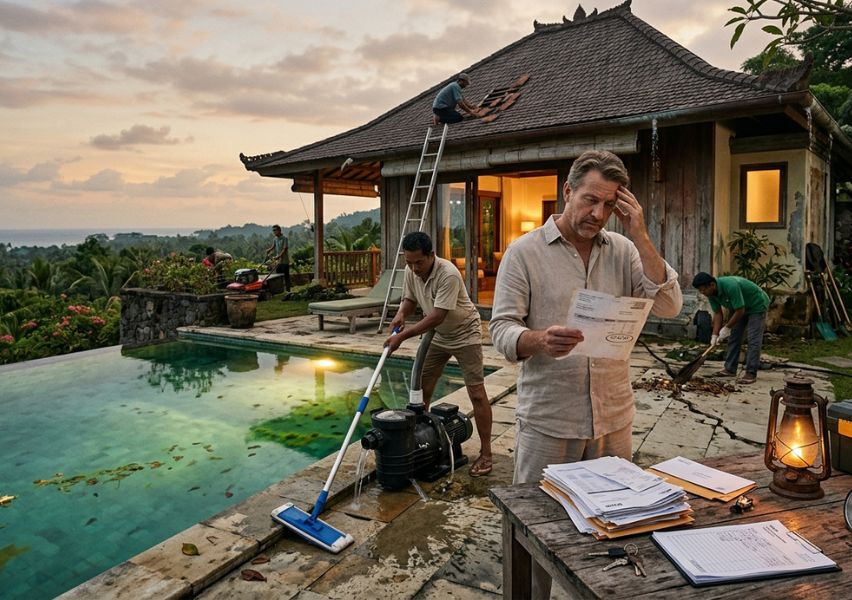
Imagine this scenario: Your villa in Seminyak is fully booked. Suddenly, an electrical short circuit causes sparks that ignite the thatched roof of the gazebo. Or, in a more common scenario, a foreign guest slips on the wet area around the pool, suffers a serious injury, and demands compensation for medical expenses.
Who is responsible for paying for the damages?
Many property investors feel secure because they already have a standard fire insurance policy when purchasing their property. However, there is one crucial fact that is often overlooked: once your villa is rented out on a short-term basis to tourists, a standard residential home insurance policy may no longer provide the coverage you expect.
As a team that regularly handles operational risk management, The Loka Management Villa always recommends that our clients separate personal residential protection from commercial property insurance.
Here is a practical guide to villa insurance in Bali and what you actually need.
Why Isn't Standard Home Insurance Enough?
Insurance companies assess the level of risk differently between homes occupied by their owners and properties operated as short-term rentals.
Commercial villas have a high turnover of guests. Guests who change every few days or weeks may be less careful when using facilities, may not know the location of emergency electrical panels, or may host parties that increase the risk of property damage.
If you submit a damage claim under a standard residential policy while the property is being listed on platforms such as Airbnb, the insurer may reject the claim on the grounds of misrepresentation, meaning that the actual use of the property was not accurately disclosed when the policy was issued.
3 Key Protections Your Policy Should Have
When discussing insurance coverage with a broker, make sure your policy includes these three key protections to properly safeguard your asset:
1. Property All Risks (PAR)
This provides coverage for physical damage to the building and its contents caused by unexpected events. In Bali, you should make sure the policy is extended to cover local geographical risks, such as:
Earthquake (EQVET): Bali is located within the Pacific Ring of Fire. Earthquake protection is therefore essential.
Special Construction Materials: If your villa uses traditional materials that are more susceptible to fire, such as thatched or alang-alang roofs, bamboo structures, or exposed timber, these materials should be disclosed from the beginning. Standard policies may exclude such materials unless specifically declared and covered.
2. Public Liability
This is one of the most important financial protections for a hospitality business. Public Liability Insurance protects you if a guest, vendor staff member, or other third party suffers an accident, injury, or loss of life within your property.
Medical evacuation costs or legal claims involving foreign nationals can potentially reach billions of rupiah. This insurance transfers that financial risk from your personal funds to the insurer, subject to the policy terms and coverage limits.
3. Business Interruption
If your villa has to close for three months because its roof collapses during a storm, you will not only have to pay for repairs and renovation, but will also lose potential rental income during the repair period.
A Business Interruption policy can provide coverage for eligible lost income during the interruption period, helping protect the cash flow of your investment while the property is being restored.
Common Gaps That Can Lead to Insurance Claims Being Rejected
Having an expensive insurance policy does not mean you can simply leave everything to the insurer. Administrative and operational requirements can often determine whether an owner's claim is accepted or rejected.
Incomplete Legal Documentation: If a villa operates without the required Building Approval (PBG) or Pondok Wisata permit, an insurer may consider the property to be operating without the necessary legal authorization for commercial use.
Lack of Maintenance Records: Insurance generally covers unexpected events and accidents, not damage resulting from neglect or normal wear and tear. For example, if a roof leaks because gutters have not been cleaned for months, the resulting claim may be rejected.
How Does Professional Management Help Protect Your Asset?
Managing insurance requirements and ensuring that a property consistently meets the conditions required for a valid claim requires a high level of operational discipline. This is where The Loka Management Villa can make a difference.
We do not sell insurance, but we help ensure that your villa's operations meet the standards that support proper risk management and insurance compliance. This includes maintaining records of AC and water pump maintenance, scheduling preventive pest control, and ensuring that electrical installations are properly maintained and protected against short-circuit risks.
When daily operations are managed according to strict standards, the risk of accidents can be significantly reduced, and the claims process, if a claim is ever necessary, can be much smoother.
Have questions about the ideal safety and operational standards for your property?
Contact The Loka Management Villa to assess the readiness of your Bali investment.